Proposal, lease, amendment, certificate, drawing or invoice.
QUOTED · CONTRACTUAL · MEASURED · CERTIFIED · BILLEDThe rate can be right.
The rate can be right.
The area can still be wrong.
Reconcile the square footage behind rent and recoveries. Keep each definition, source, standard, edition and review state visible—then price the entered difference through the actual cost timing.
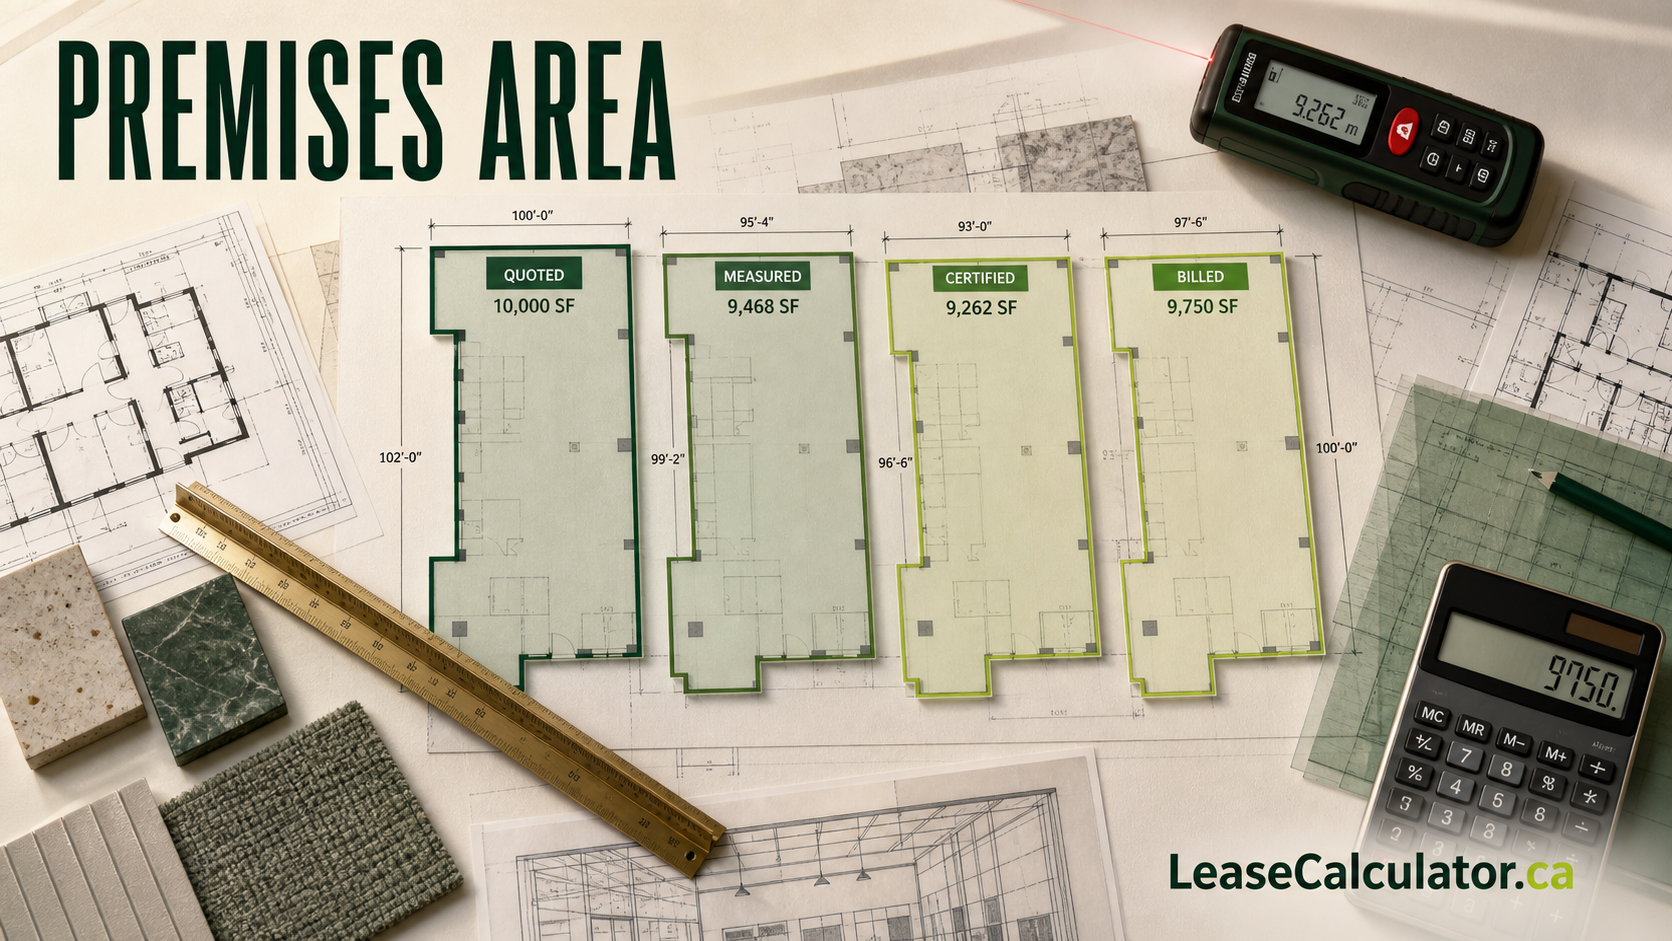
Usable, rentable, gross-leasable and gross areas are different records.
Price every per-square-foot line on its own timing and full term.
Control the source, tolerance, timing, review and next action.
ENTERED AREA EVIDENCE · LEASE RIGHTS · COST EFFECT
Reconcile the square footage before it controls the cheque.
Start from what the proposal, lease, certificate and invoice actually say. The workspace will compare like-for-like areas, price entered differences and keep every unresolved measurement or lease question visible.
Choose a template, then replace every illustrative fact.
01 · IDENTIFY THE FILE
Whose decision is this—and which premises?
A clear file identity keeps a measured area from being applied to the wrong suite, term or transaction.
02 · AREA EVIDENCE
Put every number beside its definition and source.
Quoted, contractual, measured, certified and billed areas can disagree. Do not average them or compare unlike bases.
03 · CHOOSE THE COMPARISON
Tell the tool which areas play which role.
The selection does not decide which document legally controls. It creates the arithmetic review path you want to test.
04 · LEASE & REVIEW CONTROLS
A measurement difference does not automatically change rent.
Record the right, tolerance, effective date and review status separately. These fields never create a right or serve a notice.
05 · AREA-PRICED COSTS
Give every cost its own timing.
Base rent and additional rent may increase on different dates. Enter the first increase month and repeat interval instead of assuming “annual” means the same thing everywhere.
06 · PLAIN-LANGUAGE ANSWER
The target area is 560 SF smaller than the billed area.
On the entered per-square-foot costs, the target path is $31,920 lower in the opening year and $364,894 lower over the entered term. That is a modelled effect—not an entitlement.
07 · COST PATH
See where the difference changes over time.
Each lease year reflects the entered start, end, first increase and repeat interval for every cost line.
| Lease year | Months | Current billed area | Target area | Difference | Base rent | Additional rent | Other |
|---|---|---|---|---|---|---|---|
| Year 1 | 12 | $1,242,600 | $1,210,680 | -$31,920 | -$17,920 | -$14,000 | $0 |
| Year 2 | 12 | $1,280,750 | $1,247,850 | -$32,900 | -$18,480 | -$14,420 | $0 |
| Year 3 | 12 | $1,319,391 | $1,285,498 | -$33,893 | -$19,040 | -$14,853 | $0 |
| Year 4 | 12 | $1,358,536 | $1,323,638 | -$34,898 | -$19,600 | -$15,298 | $0 |
| Year 5 | 12 | $1,398,202 | $1,362,285 | -$35,917 | -$20,160 | -$15,757 | $0 |
| Year 6 | 12 | $1,438,404 | $1,401,455 | -$36,950 | -$20,720 | -$16,230 | $0 |
| Year 7 | 12 | $1,479,158 | $1,441,162 | -$37,997 | -$21,280 | -$16,717 | $0 |
| Year 8 | 12 | $1,520,481 | $1,481,423 | -$39,058 | -$21,840 | -$17,218 | $0 |
| Year 9 | 12 | $1,562,390 | $1,522,255 | -$40,135 | -$22,400 | -$17,735 | $0 |
| Year 10 | 12 | $1,604,901 | $1,563,675 | -$41,227 | -$22,960 | -$18,267 | $0 |
08 · REVIEW QUEUE
Resolve the evidence before using the economics.
3 critical items must be resolved before the model should drive an invoice, credit, negotiation or amendment.
Confirm the source and transcription before relying on this area.
Confirm the source and transcription before relying on this area.
Reconcile the executed lease and every amendment before deciding whether an area difference changes rent or recoveries.
Confirm that a later amendment, expansion, contraction or surrender has not replaced the original area provision.
Have the operative documents reviewed before treating the modelled difference as payable or recoverable.
Confirm whether the entered area controls the tenant's share and whether the denominator changes too.
Have qualified counsel review rights, tolerance, timing, notice, waiver, estoppel and retroactivity before action.
Confirm the permitted measurement basis, notice process, adjustment direction, effective date and treatment of past invoices.
MODEL BOUNDARY
This is the control file—not the measurement certificate.
- This workspace reconciles user-entered areas, sources and cost assumptions. It does not measure a building, interpret a lease or certify an area.
- A standard name or edition is descriptive evidence only. The calculator does not reproduce or apply BOMA, IPMS or another proprietary measurement methodology.
- Different area bases are not treated as interchangeable. A usable, rentable, gross-leasable, gross or exclusive-use figure must be reconciled by a qualified measurer under the instructed basis.
- A variance outside an entered tolerance is a review signal, not proof that rent changes. Adjustment rights, effective date, retroactivity, recoveries and notice must be confirmed from the operative documents.
- Cost effects use only entered per-square-foot lines and timing. Fixed charges, percentage rent, tax and other amounts remain outside the model unless deliberately represented as an entered per-square-foot line.
The area belongs in the complete lease file.
A reconciled area can change the search brief, proposal comparison, lease draft, commencement record, invoices and operating-cost allocation. Carry the supported result forward without overwriting the source history.
Space RequirementsSeparate operational usable demand from rentable search area.→Lease AnalyzerUse the reviewed rentable area in the complete cash-flow comparison.→Lease Draft QAReconcile the premises definition and measurement mechanic before execution.→Commencement & HandoverControl post-construction measurement, possession and downstream records.→Invoice AuditTest whether current area-priced charges use the reviewed area.→Additional RentVerify the numerator, denominator and allocation methodology together.→
Connect measurement evidence to commercial lease advice
- Commercial advisory at Commercially.ca
The advisory practice behind this tool, covering occupier and owner lease strategy.
- Research industrial space on IndustrialLeasing.ca
Warehouse, flex and distribution space research for Canadian industrial requirements.
- Work with a Calgary commercial advisor
When a local Calgary advisor is the logical next step on a live requirement.