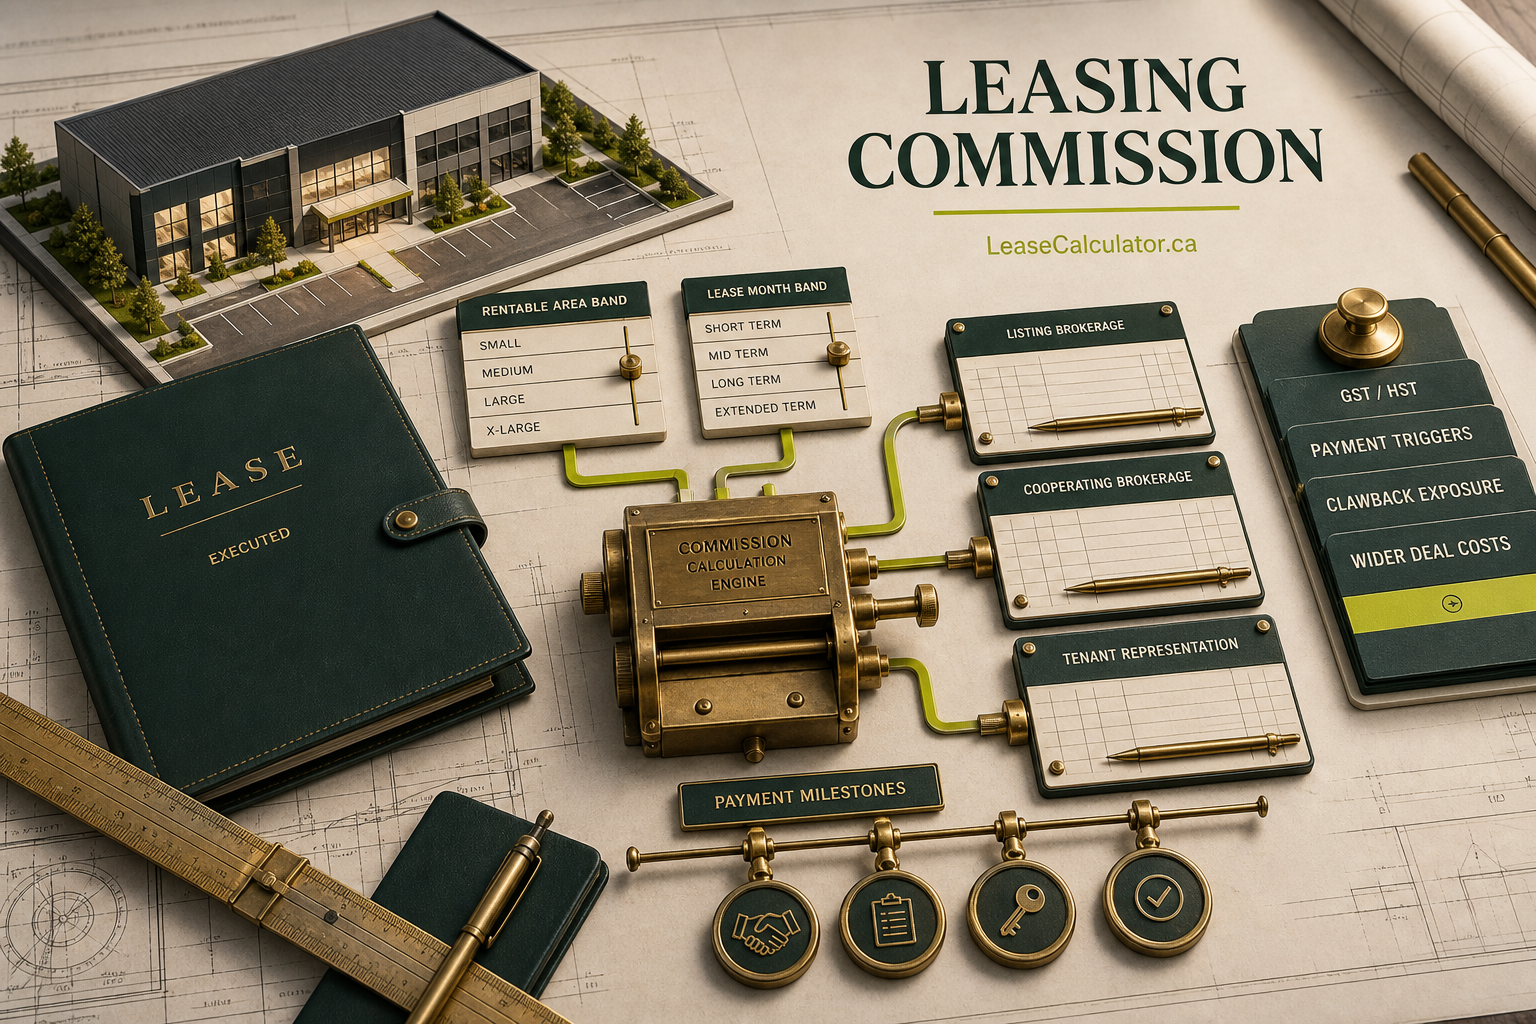
What this means for the deal
- Start with the complete signed service or commission agreement and amendment chain; do not assume a customary rate or split.
- Translate every remuneration component into an explicit method: dollars per area per lease year, percentage of base rent, percentage of gross rent or flat amount.
- Build a complete contractual rent schedule before applying a percentage and state how free rent, additional rent, expansion space and partial term bands are treated.
- Separate economic payer, contracting payer, brokerage recipient, cooperating or third-party amounts, GST/HST and cash-paid milestones.
- Treat clawback, holdover, termination, survival and dispute provisions as legal controls—not arithmetic assumptions.
Find the agreement that actually creates the fee
A leasing commission is not established by an asking brochure, market convention, email shorthand or a percentage carried from another deal. Begin with the signed service agreement, commission agreement, cooperating-broker agreement, representation agreement or other operative source. Identify the contracting parties, property, services, effective period, calculation method and circumstances in which remuneration becomes payable.
Then review amendments, extensions, renewals, expansions, terminations, side letters and transaction documents that may change the scope or trigger. Keep each version in the control file. The workbench can reproduce the treatment entered by the user, but qualified counsel and the applicable regulator must resolve ambiguity, entitlement and enforceability.
| Control | Capture | Why it matters |
|---|---|---|
| Parties | Client, brokerage, payer and other brokerage | Distinguishes the contracting obligation from the economic source of funds |
| Property and scope | Premises, transaction type, geography and services | Prevents the wrong deal or space from entering the calculation |
| Method | Exact rate, amount, rent basis and term bands | Creates reproducible arithmetic |
| Trigger | Execution, waiver, possession, commencement, opening or another event | Controls when the amount may become payable |
| Changes | Signed amendments and surviving obligations | Prevents superseded wording from governing |
Do not turn four different fee methods into one percentage
Commercial leasing fees can be expressed as dollars per square foot per lease year, a percentage of aggregate base rent, a percentage of a broader rent base, a fixed amount or a combination of methods. A stepped schedule may use one rate for the first term band and another for later years. Renewal, expansion, contraction and extension areas may carry different treatment.
Create one line for each distinct method, recipient, payer, area or month band. A single blended percentage may reproduce a total while destroying the agreement logic needed to review an invoice, amendment or clawback later.
- For dollars per square foot per lease year: controlled area × rate × applicable months ÷ 12.
- For percentage of base rent: the rate applies only to the entered base-rent cash flow within the line’s term scope.
- For percentage of gross rent: define whether the agreement actually includes additional rent, operating costs, taxes, parking, storage or other amounts.
- For flat fees: keep the contractual trigger and scope even when no rent schedule drives the amount.
- For hybrid agreements: use separate lines so every component remains independently testable.
Aggregate rent is a schedule, not a single annual number
A rent-percentage fee is only as reliable as its underlying schedule. Enter every lease month once. Separate base rent from additional rent and preserve the contractual treatment of free rent, abatement, fixturing, delayed commencement, partial months, stepped rent and expansion space.
Do not assume that a free-rent period reduces the commission basis. Some agreements may calculate on stated rent before abatement; others may use rent actually payable or a specially defined rental value. Record the entered treatment and its source rather than treating the calculator default as authority.
Contracting payer, economic payer and recipient are not always the same
Separate the listing brokerage, cooperating brokerage, tenant-representation brokerage, referral recipient and any other remuneration. Also identify whether the landlord, tenant or a third party economically bears each amount. A landlord-funded amount may satisfy all, part or none of a tenant’s separate contractual obligation depending on the agreements and jurisdiction-specific rules.
Keep the total brokerage remuneration distinct from any internal salesperson allocation. The public workbench is built for the transaction-level obligation and payment file; it does not model employment, team or brokerage-compensation arrangements.
- Record third-party remuneration and referrals separately from client-paid fees.
- Preserve any required written disclosure and the amount or method disclosed.
- Reconcile a client shortfall, credit or rebate as an explicit signed item—not an invisible netting entry.
- Do not represent that commission rates or splits are fixed, standard or regulator-approved.
Show tax beside the fee without choosing the answer
GST/HST can materially change the invoice and payment schedule. The workbench applies only the user-entered rate to lines marked taxable and keeps that amount separate from commission before tax. It does not determine registration, place of supply, input-tax-credit eligibility or whether a particular adjustment shares the same treatment.
Confirm the current rate and invoicing treatment with a qualified tax adviser and official Canada Revenue Agency guidance. Preserve the tax registration details, invoice date, supply description and any credit note in the accounting file.
A calendar date organizes the file; the signed trigger creates the question
Break the total into the instalments required by the agreement. Common transaction events can include an unconditional lease, waiver of conditions, possession, lease commencement, premises delivery, store opening or rent commencement. The relevant source may use a different event or require an invoice, direction, receipt or other condition.
For every milestone, capture the trigger wording, administrative due date, allocation percentage, invoice status, cash paid and exact source. Confirm that allocations total 100% of the selected before-tax or tax-included basis. An overdue flag is an administrative exception only; it does not establish that the legal trigger occurred.
| Field | Meaning | Do not confuse it with |
|---|---|---|
| Contractual trigger | Event stated in the signed agreement | An internal target date |
| Administrative due date | Date used to manage follow-up | A legal conclusion about entitlement |
| Allocation | Share of the selected total basis | Cash actually received |
| Status | Planned, invoiced, paid, held or waived | Proof that the underlying condition occurred |
| Paid amount | Cash entered on the selected tax basis | Revenue recognition or trust accounting treatment |
Unearned exposure is not the same as a recoverable legal claim
A commission agreement may address early termination, tenant default, non-commencement, surrender or another event. Any repayment may depend on precise wording, causation, timing, notice, cure, settlement and other facts. Do not infer a clawback merely because the lease ended early.
Use straight-line vesting only as a disclosed planning convention when it matches the business case, or enter an externally reviewed unearned percentage. Then apply the entered recoverable share only to fee lines marked eligible. Keep tax adjustments, legal costs and collected amounts outside the model unless separately supported.
Commission belongs inside the transaction-cost stack
For a landlord, commission may sit beside tenant improvements, free rent, legal documentation, marketing, project management, fit-up coordination and other leasing capital. For a tenant, representation fees may sit beside legal review, due diligence, design, moving and change-management costs. Comparing commission alone can miss the real cash requirement.
Add costs and signed credits separately, identify the economic payer, state whether the entered tax rate applies and preserve the approval or invoice source. The total is a cash-planning view—not accounting classification, deductibility, capital-cost treatment or recoverability advice.
Make the calculation reproducible after the deal team moves on
Export the commission-line detail, rent basis, payment milestones and review queue. Retain the signed agreements, amendments, lease or renewal instrument, area confirmation, rent schedule, required disclosures, invoices, tax details, payment evidence, credit notes and dispute correspondence under the organization’s approved retention policy.
Record who reviewed the business calculation, tax treatment and legal trigger. If the invoice differs from the reconstructed amount, preserve both values and the resolution; do not overwrite history. Move outstanding payment or clawback obligations into the lease-administration register with an accountable owner.
Frequently asked questions
What is a typical commercial leasing commission in Canada?+
There is no universal platform default. Rates, methods, splits and payment triggers are negotiated and can be affected by the signed agreement and applicable provincial regulation. Enter the actual controlled method rather than a supposed standard rate.
Can I calculate commission as dollars per square foot per year?+
Yes. The workbench multiplies the controlled area by the entered annual rate and the applicable lease months divided by twelve. Separate later term bands, renewal periods or expansion space when they use different rates or areas.
Does free rent reduce a percentage-of-rent commission?+
Only if the controlling agreement supports that treatment. The rent schedule includes an entered free-base-rent percentage so the model can reproduce the reviewed interpretation without assuming it universally applies.
Should additional rent be included in gross-rent commission?+
The signed definition controls. The workbench can apply a percentage to entered base rent plus entered additional rent, but users must confirm which charges the agreement includes and avoid treating the label gross rent as self-defining.
How does the calculator handle GST/HST?+
It applies the user-entered rate only to lines marked taxable and displays tax separately. It does not choose a rate, determine registration, place of supply, invoicing treatment or input-tax-credit eligibility.
Can it split listing and cooperating commission?+
Yes. Create separate lines with their own method, rate, term scope, payer and source. The result preserves each transaction-level amount rather than hiding the split in one blended total.
Does an overdue flag mean the commission is legally payable?+
No. The flag compares the entered administrative date and payment to the modelled allocation. The signed trigger, transaction facts, notices, disputes and applicable law require professional review.
What does the clawback result mean?+
It is an entered planning exposure based on straight-line vesting or an entered unearned percentage, the selected recoverable share and eligible fee lines. It is not a finding that repayment is legally owed or collectible.
Where the factual guidance comes from
These links support narrow factual points in this guide. They do not replace review of the proposal, executed lease or advice for the actual transaction.
Real Estate Council of Alberta — Real Estate Act Rules ↗Official Alberta rules including written-service-agreement content such as the amount or method of calculating remuneration and the circumstances when it is payable. Confirm the current rule and transaction-specific application.Real Estate Council of Alberta — Real Estate Act ↗Official Alberta statute source addressing commission recovery and prohibited calculation structures. It does not determine entitlement in a particular file.Real Estate Council of Ontario — Representation agreements ↗Official Ontario regulatory bulletin describing remuneration-method, change-circumstance and payment-method content and warning against suggesting remuneration is fixed or regulator approved.BC Financial Services Authority — Remuneration information ↗Official British Columbia guidance on service-agreement remuneration, cooperating brokerage amounts, third-party remuneration and written disclosures.Competition Bureau Canada — Pricing and compensation in real estate ↗Official federal competition-policy discussion stating remuneration type is negotiable within legal limits and emphasizing independent market pricing rather than fixed or suggested rates.Canada Revenue Agency — GST/HST in special cases ↗Official CRA overview addressing GST/HST on commissions and related agent services. Current transaction-specific advice remains necessary.Canada Revenue Agency — GST/HST place-of-supply rules ↗Official source for place-of-supply considerations. The workbench deliberately does not select the applicable rate.LeaseCalculator.ca — Calculation methodology ↗The platform’s disclosed fee formulas, rent-basis, tax, payment, clawback and device-local boundaries.This guide is general educational information and financial-workflow support. It is not legal, tax, accounting, engineering, environmental, appraisal or brokerage advice. Verify source documents and obtain appropriate professional advice before acting.